
Conventional Loans Michigan
Expert guidance from Edward Kalavitz — dual-licensed Michigan Realtor and Mortgage Loan Originator with 25+ years of experience helping Michigan families.
Realtor License #6501386956 | Turnkey Realty LLC • NMLS #138424 | Private Mortgage Guarantee LLC
In This Guide
- Today’s Mortgage Rates
- Weekly Rates Email
- Michigan Mortgage Advisor
- Browse Active Homes
- What Are Conventional Loans Michigan…
- Why Choose Conventional Loans Michigan…
- Conventional Loans Michigan Requirements for…
- Types of Conventional Loans Michigan…
- Conventional Loans Michigan Down Payment Options
- Private Mortgage Insurance (PMI) Explained
- Benefits of Conventional Loans Michigan…
- How to Apply for Conventional Loans Michigan
- Watch: Meet Edward
- What Clients Say
- FAQ
- Available Hours
Mortgage Rates in Michigan
Competitive pricing personalized to your scenario. Rates shown reflect 740+ credit, 30-year fixed terms unless noted.
Purchase Loans
Conventional Purchase
15-Year Conventional
FHA 30-Year Purchase
VA 30-Year Purchase
USDA Purchase & Refinance
USDA 30-Year Purchase
FHA Streamline Refi
Conventional Refinance
Jumbo & High-Balance
Jumbo / High-Balance
Want Weekly Michigan Mortgage Rate Updates?
Get current rates delivered every Tuesday morning. Stay informed without checking rate sites all week.
From Edward Kalavitz, NMLS #138424. Unsubscribe anytime.
Not Sure Which Loan You Qualify For?
See the rates. Not sure which loan fits your situation? The Michigan Mortgage Advisor answers that in 60 seconds — analyzing your credit, down payment, and goals to recommend the best loan program and show you your real monthly payment on a Michigan home.
- Instant loan-type recommendation — FHA, VA, USDA, or Conventional
- Live rate and APR for your exact scenario
- Michigan-specific closing cost estimate
- No credit check required to start
Best-fit loan: matched to you
Your down payment
Your real monthly payment principal + interest
Your actual recommendation is calculated live based on your inputs.
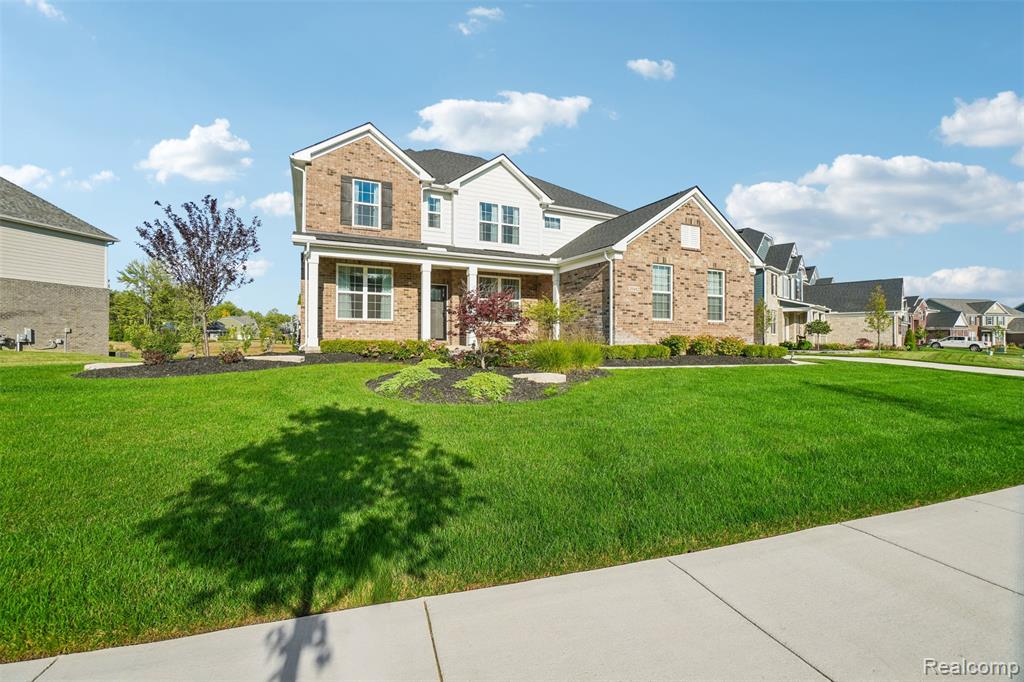
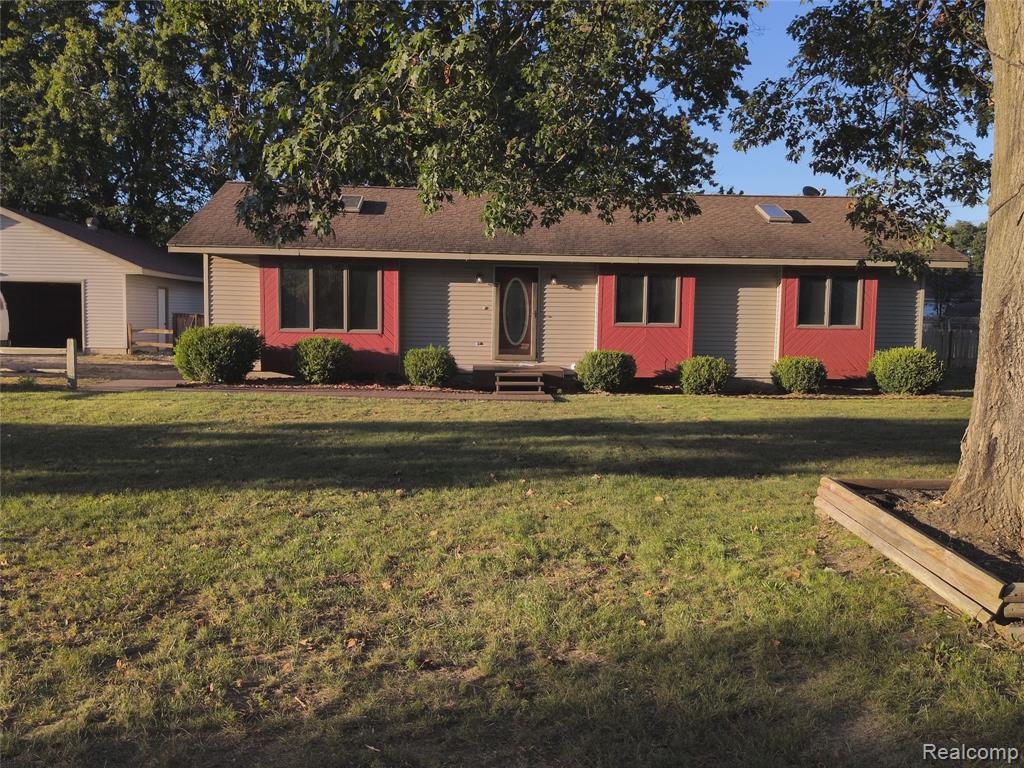
Browse Active Michigan Homes
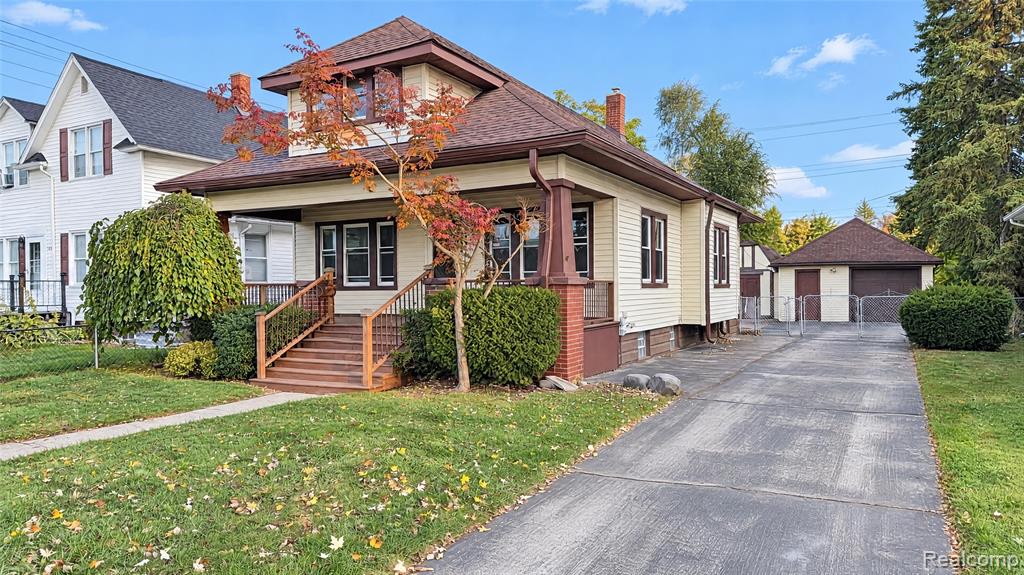 Open House
$145,000
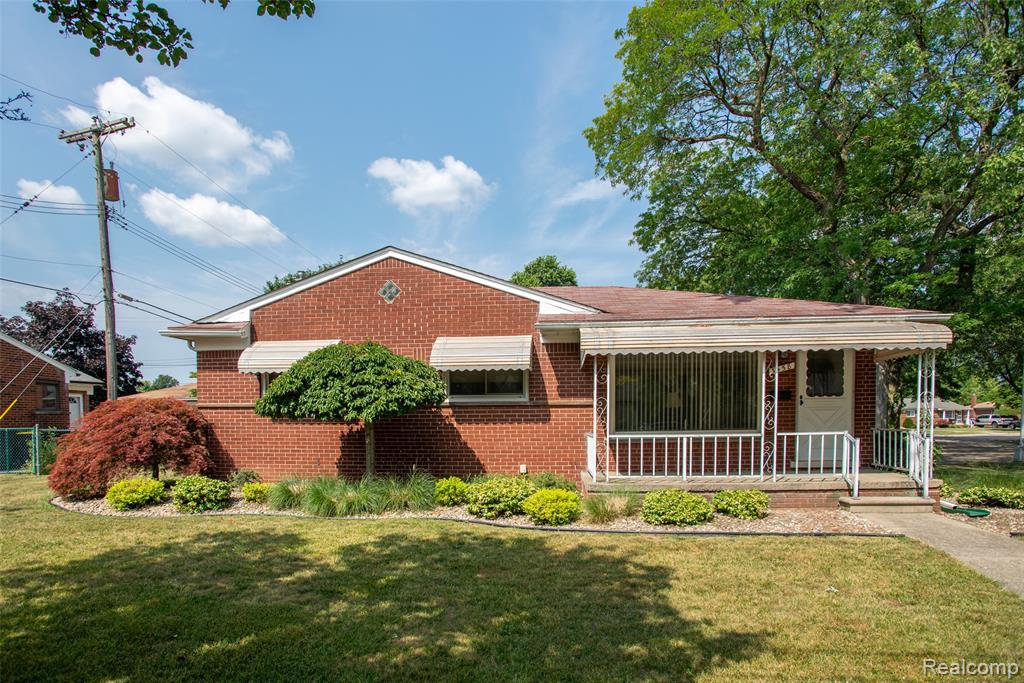
 Open House
$994,000
 New Listing
Open House
$320,000

 Open House
$210,000
 Open House
$135,000

Edward Kalavitz
Realtor & Mortgage Expert
What Are Conventional Loans Michigan Homebuyers Need to Know?
Conventional loans Michigan homebuyers choose are mortgages that are not insured or guaranteed by the federal government. Unlike FHA, VA, or USDA loans, conventional mortgages are backed by private lenders and follow guidelines set by Fannie Mae and Freddie Mac.
Conventional loans Michigan borrowers prefer are the most common type of mortgage in America, representing about 70% of all home loans. They offer competitive interest rates, flexible terms, and the ability to remove mortgage insurance once you reach 20% equity — a major advantage over government-backed loans. As your Michigan real estate expert, I can help you determine if this option is right for your situation.
Why Choose Conventional Loans Michigan Homebuyers Prefer?
This loan type offers numerous advantages for qualified Michigan buyers:
- Low Down Payment Options: As little as 3% down for qualified buyers
- Competitive Interest Rates: Often lower than FHA rates for borrowers with good credit
- PMI is Removable: Cancel private mortgage insurance at 20% equity
- Higher Loan Limits: Up to $832,750 in Michigan (2026)
- Flexible Property Types: Primary homes, second homes, investment properties
- No Upfront Mortgage Insurance: Unlike FHA’s 1.75% upfront premium
- Faster Closing Times: Typically 21-30 days
Use our mortgage calculator to estimate your monthly payments with different down payment amounts.
💡 Best for Borrowers with Good Credit
If you have a credit score of 680 or higher, conventional loans Michigan lenders offer will typically give you better rates and terms than an FHA loan. The higher your credit score, the more you’ll save over the life of the loan!
Conventional Loans Michigan Requirements for 2026
Here are the current requirements borrowers must meet:
| Requirement | Details |
|---|---|
| Credit Score | Minimum 620 (680+ for best rates) – Learn more |
| Down Payment | 3% minimum (5%, 10%, or 20% for better terms) – Down payment help |
| Debt-to-Income Ratio | Maximum 43-45% (some exceptions to 50%) – DTI guide |
| Employment History | 2 years steady employment or income – Verification info |
| Property Requirements | Must meet appraisal standards |
| Reserves | 2-6 months recommended (varies by loan type) |
| Loan Limits (2026) | $832,750 (Michigan single-family) |
Types of Conventional Loans Michigan Borrowers Can Choose
Conforming vs. Non-Conforming Loans
Conforming Loans
Meet Fannie Mae and Freddie Mac guidelines.
- Loan amounts up to $832,750 (Michigan, 2026)
- Meet credit and income requirements
- Follow standard underwriting guidelines
- Typically offer the best rates
Non-Conforming Loans
Exceed conventional limits.
- Jumbo loans (over $832,750)
- Unique property types or situations
- May have stricter requirements
Fixed-Rate vs. Adjustable-Rate Mortgages (ARMs)
Fixed-Rate Mortgages
Interest rate stays constant for the entire loan term.
- Rate stays the same for entire loan term
- Most popular: 30-year and 15-year terms
- Predictable monthly payments
- Best for long-term homeowners
Adjustable-Rate Mortgages (ARMs)
Lower starting rate that adjusts after a fixed period.
- Lower initial interest rate
- Rate adjusts after fixed period (5/1, 7/1, 10/1 ARMs)
- Good for short-term ownership (5-7 years)
Conventional Loans Michigan Down Payment Options
Conventional loans Michigan lenders offer have flexible down payment options:
| Down Payment | PMI Required? | Best For |
|---|---|---|
| 3% | Yes | First-time buyers, limited savings |
| 5% | Yes | Slightly lower PMI, more equity |
| 10% | Yes | Lower PMI rates, better loan terms |
| 20% | No | No PMI, lowest rates, best terms |
| 25%+ | No | Investment properties, vacation homes |
Need help with your down payment? Explore Michigan down payment assistance programs.
Private Mortgage Insurance (PMI) Explained
If you put down less than 20% on a conventional loan, you’ll pay Private Mortgage Insurance (PMI) to protect the lender. Learn how PMI works from the Consumer Financial Protection Bureau. Here’s what you need to know:
PMI Costs
- Rate: 0.3% to 1.5% of loan amount annually
- Payment: Added to monthly mortgage payment
- Example: $250,000 loan at 0.5% PMI = $104/month
When PMI Can Be Removed
- Request Removal: At 20% equity (80% loan-to-value)
- Automatic Termination: At 22% equity
- Faster Removal: Home appreciation or extra principal payments
💡 PMI Removal Advantage
Major benefit over FHA! Conventional loans Michigan borrowers choose allow PMI removal at 20% equity. FHA mortgage insurance stays for the life of the loan if you put down less than 10%. This can save you thousands of dollars! Schedule your annual mortgage review to track your equity.
Benefits of Conventional Loans Michigan Homebuyers Enjoy
✓ Major Benefits
- ✓PMI removable at 20% equity
- ✓Competitive interest rates
- ✓No upfront mortgage insurance
- ✓Higher loan limits ($832,750)
- ✓Works for any property type
- ✓Faster closing (21-30 days)
- ✓Best rates for good credit
- ✓Flexible down payment options
- ✓Investment property eligible
⚠️ Considerations
- ⚠Higher credit score required (620+)
- ⚠Larger down payment recommended
- ⚠Stricter qualification standards
- ⚠PMI required under 20% down
- ⚠May require reserves
- ⚠Not ideal for low credit scores
How to Apply for Conventional Loans Michigan
The application process is straightforward when you work with an experienced broker:
- Pre-Qualification: Initial financial review (15 minutes)
- Gather Documents: W-2s, pay stubs, bank statements, tax returns
- Complete Application: Full 1003 loan application
- Credit Check: Lender pulls credit report and score
- Pre-Approval: Conditional approval with verification (24-48 hours)
- Home Shopping: Find your perfect home
- Purchase Agreement: Make offer and negotiate
- Appraisal Ordered: Property appraisal scheduled
- Underwriting Review: Detailed loan review (3-7 days)
- Clear to Close: Final approval received
- Closing Day: Sign documents and get keys! Review closing costs
Timeline: Conventional loans Michigan typically close in 21-30 days from application — faster than FHA or USDA. Check our mortgage FAQ for more details.
Conventional vs. FHA Loan Comparison
See how this program compares to FHA:
| Feature | Conventional Loan | FHA Loan |
|---|---|---|
| Min. Down Payment | 3% | 3.5% |
| Min. Credit Score | 620 (680+ for best rates) | 580 |
| Upfront Insurance | None | 1.75% of loan amount |
| Monthly Insurance | PMI (removable at 20% equity) | MIP (life of loan if <10% down) |
| Loan Limits | $832,750 | $541,287 |
| Best For | Good credit, higher income | Lower credit, first-time buyers |
Not sure which loan is best? Contact me for a free consultation to compare your options. Verify my credentials through NMLS Consumer Access.
⚠️ Credit Score Matters!
Your credit score significantly affects your interest rate on conventional loans Michigan. The difference between a 680 and 760 credit score can save you tens of thousands of dollars over the life of your loan. I can help you improve your credit before applying!
Conventional Loan Limits Michigan (2026)
Current limits for conventional loans Michigan borrowers can access:
- All Michigan Counties: $832,750 (single-family)
- 2-Unit Properties: $1,066,250
- 3-Unit Properties: $1,288,800
- 4-Unit Properties: $1,601,750
Loans above these amounts are considered “jumbo loans” and have different requirements. I serve all 83 Michigan counties including Grand Rapids, Kalamazoo, Holland, and Muskegon.
Why Michigan Buyers Choose Edward Kalavitz for Conventional Loans
Michigan buyers who choose conventional loans michigan through Edward Kalavitz benefit from 25+ years of experience comparing loan programs to find the option that saves the most money. Conventional loans michigan offer several advantages over government-backed programs, including the ability to cancel private mortgage insurance once you reach 20 percent equity and often lower total costs for buyers with strong credit scores.
As a dual-licensed Realtor (#6501386956, Turnkey Realty LLC) and Mortgage Loan Originator (NMLS #138424, Private Mortgage Guarantee LLC), Edward provides conventional loans michigan clients with comprehensive service under one roof. He evaluates your financial profile, compares conventional loans michigan financing against FHA and other programs, processes your pre-approval, and guides your entire home purchase from offer through closing.
Conventional loans michigan are particularly attractive for buyers with credit scores above 680, where interest rates are most competitive. For buyers with 740 or higher credit, conventional loans michigan typically offer the lowest rates and best terms available in the Michigan market. Edward shops your conventional loans michigan application across multiple wholesale lenders to ensure you get the best rate possible.
Conventional Loans Michigan vs FHA — Which Is Better?
One of the most common questions Edward receives is whether conventional loans michigan or FHA loans are the better choice. The answer depends on your specific financial situation. For buyers with credit scores below 680, FHA loans typically offer better rates and easier qualification. For buyers with scores above 680 and at least 5 percent down, conventional loans michigan often cost less over the life of the loan because PMI can be removed at 20 percent equity while FHA mortgage insurance is permanent on most loans.
Edward runs both conventional loans michigan and FHA scenarios side by side for every buyer so you can see the actual numbers and make an informed decision. This comparison includes monthly payments, total interest, mortgage insurance costs, and the breakeven point. Use the mortgage calculator to model scenarios, or the DTI calculator to check your qualification.
Michigan Communities Popular with Conventional Loan Buyers
Conventional loans michigan are popular across all Michigan communities, especially where home prices align well with conforming loan limits. Grand Rapids, Kalamazoo, Holland, and Traverse City all have median home prices well within conventional loan limits, making conventional loans michigan an excellent choice.
Edward serves conventional loans michigan clients across all 83 counties. Available weekdays 8 AM to 8 PM, weekends 9 AM to 8 PM, and every holiday. Call (616) 633-3692 to discuss your options. Learn more about Edward, read reviews, or explore all 19 free tools. Visit MSHDA for Michigan programs.
Understanding Conventional Loan Limits in Michigan
Conventional loans michigan have conforming loan limits set by the Federal Housing Finance Agency (FHFA) that determine the maximum loan amount available without requiring jumbo financing. For 2026, the conforming loan limit in most Michigan counties is $832,750 for a single-family home. This limit covers the vast majority of home purchases across the state, making conventional loans michigan accessible for buyers at nearly every price point.
For buyers who need to borrow more than the conforming limit, jumbo loans michigan are available through Edward Kalavitz with competitive rates and terms. However, most Michigan buyers will find that conventional loans michigan conforming limits are more than sufficient for their purchase.
Conventional Loan Property Types in Michigan
Conventional loans michigan can be used to purchase a wide range of property types, giving buyers more flexibility than some government-backed programs. Eligible property types include single-family homes, condominiums (including non-warrantable condos with some lenders), townhouses, two-to-four unit properties (with owner occupancy), and planned unit developments. This flexibility makes conventional loans michigan popular with both first-time buyers and experienced investors.
Unlike FHA loans which have strict property condition requirements, conventional loans michigan have fewer property restrictions. The home must meet basic safety and habitability standards, but the appraisal process for conventional loans michigan is generally less restrictive than FHA or VA appraisals. This gives buyers access to a wider range of properties including fixer-uppers and homes that might not pass a government loan appraisal.
Refinancing with Conventional Loans Michigan
Conventional loans michigan are not just for purchases. Many Michigan homeowners use conventional refinancing to lower their interest rate, change their loan term, or access home equity through a cash-out refinance. Edward Kalavitz handles conventional refinances through Private Mortgage Guarantee LLC and can evaluate whether refinancing your current mortgage into a new conventional loan makes financial sense. Use the conventional refinance calculator to estimate your potential savings.
Talk to Edward Kalavitz About Conventional Loans Michigan
25+ years of Michigan experience. Dual-licensed Realtor and Mortgage Loan Originator. Free consultation, available 7 days a week.
Get Pre-Approved Free Contact Edward Call (616) 633-3692Watch: Meet Edward
Get to know Edward Kalavitz — one dual-licensed professional handling both the real estate and the mortgage side of your Michigan home purchase or refinance.
What Clients Say About Working with Edward
Edward is a dual-licensed Realtor & Mortgage Loan Originator. Reviews include clients from both his real estate and mortgage practices.
“Very Professional and Thorough”
“Edward is very professional and thorough. Had a great experience working with him. Everything went very smooth.”
— Susan Parsley | Google Review
“Works Hard 24/7”
“Ed is wonderful to work with! He is very thorough, experienced, and friendly. Ed works hard 24/7 to give you the best mortgage experience and is always able to help with whatever you need!”
— Justin Schneider | Google Review
“Great to Have 2 in 1”
“Ed was very responsive, knowledgeable, and made our first home buying experience great! He’s a relator and lender, which was great to have “2 in1”. We were able to look at houses and run number the same day. He was very flexible with times we needed to set up showings, as well as very informative and organized with paperwork! I appreciate his expertise greatly!”
— Mallory Anderson | Google Review
“Above and Beyond”
“Edward is a great relator and loan officer. He helped my fiance and I buy our first home. We called him back when we were ready to sell and buy our forever home. He again went above and beyond to make the process swift and easy. I recommend him to my friends and family who are looking into buying, selling or refinacing their home!”
— Anthony Smolenski | Google Review
“Closing Came Sooner Than Anticipated”
“Edward was up front, professional and most helpful in first determining if I was a good candidate for a mortgage re-Fi. My case was Probably not the easiest , however, he made my “homework” manageable. The closing came sooner than anticipated , thanks to his perseverance, knowledge and professionalism .”
— Dennis Bowman | Refinance Client | Google Review
“Not Only My Realtor — My Friend”
“Edward was an excellent help in the most stressful time of my life. My son passed away in 2018 and I had to sell his home. Edward alleviated some stress by being patient, organized and communicated thoroughly the entire process. He not only was my realtor/loan officer but he was my friend! Highly recommend him for any home needs!”
— Paula Hilliard | Google Review
Conventional Loans Michigan FAQ
QWhat credit score do I need for conventional loans in Michigan?
Most lenders require a minimum credit score of 620 for conventional loans Michigan. However, better rates and terms are available with scores of 680 or higher. The higher your score, the lower your interest rate. At 740+, you’ll qualify for the best rates available.
QHow much down payment is required for conventional loans Michigan?
You can get conventional loans Michigan with as little as 3% down for primary residences. Putting down 5%, 10%, or 20% will reduce your monthly payment and may eliminate PMI. For investment properties, you’ll typically need 15-25% down. Explore down payment assistance options.
QCan I remove PMI from conventional loans in Michigan?
Yes! This is one of the biggest advantages of conventional loans Michigan borrowers enjoy. Once you reach 20% equity — through paying down the loan or home appreciation — you can request PMI removal. It automatically terminates at 22% equity. This is a major advantage over FHA loans, where mortgage insurance stays for the life of the loan.
QWhat’s the difference between conventional and FHA loans in Michigan?
Conventional loans Michigan aren’t government-insured, require higher credit scores (620+), have no upfront mortgage insurance, and allow PMI removal at 20% equity. FHA loans are government-backed, accept scores as low as 580, charge 1.75% upfront mortgage insurance, and keep it for the life of the loan.
QWhat are the conventional loan limits in Michigan for 2026?
For 2026, the conforming loan limit in Michigan is $832,750 for single-family homes. Loans above this amount are considered “jumbo loans” with different requirements. Multi-unit properties have higher limits.
QHow long does it take to close conventional loans in Michigan?
Conventional loans Michigan typically close in 21-30 days — faster than FHA or USDA loans (30-45 days). With a clean application and quick document submission, some close in as little as 14-21 days. Review our closing costs guide.
QCan I use conventional loans for investment properties in Michigan?
Yes! Conventional loans Michigan investors use are available for primary residences, second homes, and investment properties. Investment properties typically require 15-25% down and carry slightly higher rates. DSCR loans are also available for investors.
QAre conventional loans better than FHA for first-time buyers in Michigan?
It depends on your credit score. With a 680+ score, conventional loans Michigan often offer better rates and removable PMI. Below 680, FHA may provide better terms. As a first-time buyer, I can help you compare both options to find the best fit.
Buy or Sell a Michigan Home with Edward Kalavitz
Dual-licensed Realtor & Mortgage Loan Originator — one trusted professional for your entire Michigan transaction.
Available When You Need Answers
Real estate questions don’t wait for business hours — and neither does Edward Kalavitz.

